By Global Entertainment Desk
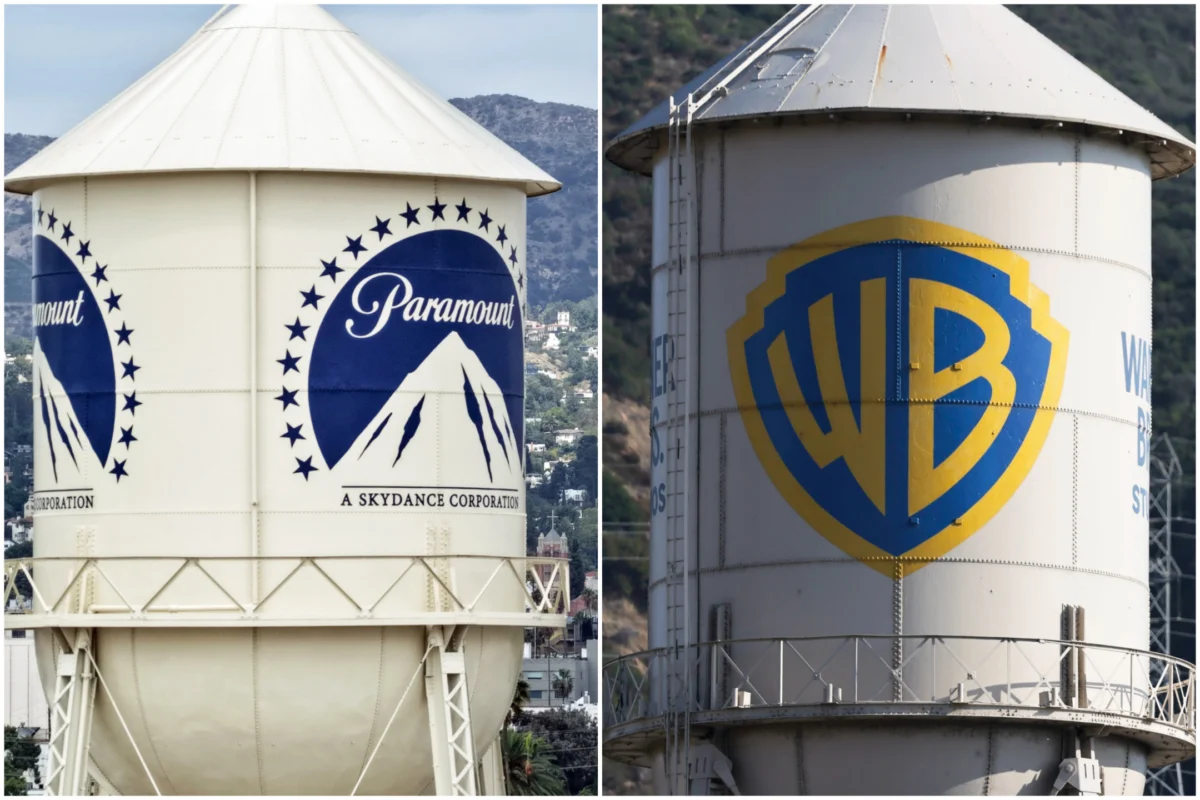
In its maiden financial reporting period following one of the most transformative corporate consolidations in media history, Skydance has revealed a foundational profitability milestone for its legacy Paramount operations while offering a candid look into the massive structural recalibration now underway. Fresh from finalizing its blockbuster merger with Warner Bros. Discovery, the newly expanded conglomerate announced that the Paramount segment of the business generated a net profit of $73 million.
This figure represents a dramatic and welcome turnaround from the substantial net loss recorded in the corresponding period a year earlier. However, the reported financial data carries an important caveat: the newly integrated assets from the Warner Bros. Discovery transaction were officially excluded from these specific metrics. Because the merger deal did not officially cross the finish line until October—falling just outside the parameters of the recently concluded fiscal quarter—the full scope of the combined corporate behemoth remains to be captured in subsequent financial disclosures.
Even in the absence of the Warner Bros. properties, the current operational architecture is staggering. The parent company—now home to iconic legacy brands including CBS, CNN, Paramount Pictures, and the Warner Bros. film and television studios—reported an overall quarterly revenue figure of $7.03 billion. This represents a solid 5% top-line increase compared to the same period in the prior fiscal year. On a per-share basis, net income landed at six cents, a figure that expands dramatically to 45 cents per share when adjusted for pre-tax expenses, integration outlays, and various non-recurring restructuring costs.
Yet, beneath the headline-grabbing swing to profitability lies a complex narrative of transitioning business models. While the company’s digital streaming apparatus is accelerating at an impressive clip, its traditional linear television foundations continue to face acute, secular headwinds. As leadership under Chief Executive David Ellison looks toward a future defined by a targeted $6 billion in run-rate synergies, the entertainment industry is watching closely to see how this newly minted titan will balance aggressive cost-cutting with high-stakes creative investment.
Main Facts
The foundational takeaways from Skydance’s latest financial disclosure underscore a company caught in the vital crosscurrents of media evolution:
- Profitability Turnaround: The legacy Paramount operations generated a net profit of $73 million, marking a decisive swing back into the black compared to the loss reported during the same period in the previous year.
- Exclusion of Warner Bros. Assets: Due to the October closing date of the merger—which fell after the conclusion of the fiscal quarter—the financial results do not yet incorporate data from the newly acquired Warner Bros. Discovery properties.
- Top-Line Growth: Total corporate revenue reached $7.03 billion, representing a 5% year-over-year increase.
- Per-Share Metrics: Net income was reported at six cents per share, climbing to 45 cents per share on an adjusted basis when accounting for pre-tax and non-recurring expenses.
- Diverging Divisional Fortunes: While Direct-to-Consumer (DTC) and Studio revenues experienced healthy gains, the traditional TV division suffered a 7% decline.
- Synergy Targets: Executive leadership reaffirmed its aggressive financial target of achieving at least $6 billion in run-rate synergies—net of reinvestment—across the consolidated cost structure within a three-year window.
Chronology of Events
To understand how Skydance reached this pivotal financial juncture, it is necessary to examine the sequence of corporate maneuvers that have reshaped the entertainment landscape over the past year:
- Early 2025: Operational pressures mount across the traditional media sector, prompting strategic explorations of consolidation among mid-sized and major Hollywood players.
- October 2025: As part of ongoing portfolio optimization and debt management within the legacy framework, operations begin shifting, highlighted by the strategic sale of the Telefe network.
- Mid-2025 to Late 2025: Regulatory reviews and shareholder negotiations regarding the massive Skydance and Warner Bros. Discovery merger reach critical milestones, laying the groundwork for a combined entity with an expense base exceeding $50 billion.
- January 2026: The strategic divestiture timeline continues with the sale of Chilevisión, impacting overall advertising revenue comparables for the traditional broadcast division.
- October 2026 (Fiscal Quarter Boundary): The historic merger between Skydance and Warner Bros. Discovery officially closes, legally binding two major Hollywood studio systems, television portfolios, and streaming operations together.
- Post-October 2026: The current reporting period closes. Because the deal finalized after the fiscal period ended, the newly integrated Warner Bros. assets are omitted from the current financial statements, setting the stage for a massive combined reporting debut in the next quarter.
Supporting Data and Divisional Breakdown
A granular examination of the financial report reveals a tale of two distinct media ecosystems: a legacy broadcast structure in structural decline, offset by a surging digital streaming apparatus and a robust third-party production studio business.
Traditional Television Division
Skydance’s largest traditional operating segment continued to face stiff macroeconomic and secular headwinds. Total revenue for the traditional TV division fell 7% to $3 billion. Within this segment:
- Advertising Revenue: Dropped by 8%. Company executives noted that this decline was exacerbated by strategic asset realignments, specifically the sale of Telefe in October 2025 and Chilevisión in January 2026.
- Distribution Revenue: Slipped 5%, driven primarily by the ongoing, industry-wide phenomenon of traditional subscriber erosion (cord-cutting).
Direct-to-Consumer (DTC) Operations
In stark contrast to the linear TV declines, the company’s streaming segment served as a primary engine of growth. DTC revenue rose 11% to reach $2.5 billion.
- Paramount+ Performance: The flagship streaming service posted a stellar 21% year-over-year revenue growth rate, signaling improving monetization per user.
- Subscriber Acquisition: Total platform subscriptions expanded by approximately 6%, proving that scale is still achievable in an increasingly crowded and mature streaming market.
Studio Operations
Revenue from the studio division climbed 23% to $1.5 billion. This robust expansion was propelled in large part by aggressive licensing agreements and content production executed for third-party platforms, demonstrating the enduring global value of Skydance’s production capabilities.
Official Responses and Shareholder Communications
In their formal letter to shareholders, executives provided a transparent, unvarnished assessment of the multi-studio landscape they now oversee. The tone of the communication was pragmatic, acknowledging short-term performance disparities while laying out an ambitious roadmap for the future.
Most notably, management drew a sharp contrast between the health of its two primary film production houses. "We expect the Warner Bros. film slate in Q4 to underperform," the company stated frankly in the shareholder letter. This admission highlights the creative and commercial rebuilding process required within the newly acquired Warner Bros. assets.
Conversely, leadership offered high praise for its original banner: "Paramount Pictures continues to perform well and is expected to double its output in 2026 with 15 releases." This aggressive theatrical expansion signals that Skydance is doubling down on the big screen as a vital anchor for its broader intellectual property ecosystem.
Addressing the mechanics of the merger, executives emphasized that the union of two global streaming services, two major film and television studio groups, two extensive television portfolios, and redundant corporate functions will unlock unprecedented operational efficiencies. By rationalizing an expense base that exceeds $50 billion, management reiterated its firm commitment to extracting "at least $6 billion in run-rate synergies, net of reinvestment across our cost structure within three years."
Strategic Implications for the Media Landscape
The implications of Skydance’s latest financial report—and the broader corporate consolidation it represents—extend far beyond quarterly balance sheets, signaling a profound restructuring of the modern entertainment economy.
1. The Death of Linear Scale and the Rise of Hybrid Monetization
The 7% drop in traditional TV revenue, paired with an 8% fall in advertising, underscores the relentless pressure facing legacy broadcast and cable networks. As cord-cutting accelerates, traditional media companies can no longer rely on automatic affiliate fee increases and predictable ad spends to pad their margins. Skydance’s pivot—leaning heavily into its 11% DTC revenue growth and the 21% surge at Paramount+—proves that the future belongs entirely to digital ecosystems. However, the company’s studio division success (up 23% via third-party licensing) suggests that even in a streaming-first world, traditional content licensing remains a vital financial hedge.
2. The Hard Realities of Post-Merger Integration
While corporate mergers are routinely pitched on the promise of synergy and scale, the disclosure that the Warner Bros. film slate is expected to underperform in the fourth quarter serves as a sobering reminder of the friction involved in combining massive creative enterprises. Aligning corporate cultures, streamlining greenlight processes, and rationalizing bloated development pipelines are notoriously difficult tasks. Skydance’s leadership is signaling to Wall Street that a turnaround for the Warner Bros. brand will take time, patience, and disciplined capital allocation.
3. Theatrical Reinvention vs. Cost Discipline
Paramount Pictures’ plan to double its theatrical output to 15 releases in 2026 runs counter to the risk-averse strategies deployed by several industry competitors in recent years. By betting big on the theatrical window—while simultaneously hunting for $6 billion in cost synergies—Skydance is attempting a high-wire act: cutting fat from administrative and overlapping corporate overhead while feeding the creative engine that drives theatrical box office and downstream streaming value.
Looking Ahead
As Skydance prepares to issue its next comprehensive financial report—one that will finally incorporate the vast operational footprint of Warner Bros. Discovery—the industry will be watching to see how the $73 million profit baseline holds up under the weight of an expanded corporate structure. If management can successfully execute its synergy targets while revitalizing the underperforming Warner Bros. film slate, Skydance may well establish a new blueprint for survival and profitability in the streaming age.